Burlingame Eichlers / Insurance
The boring page that costs the most money
Two numbers, and most owners have the wrong one on the policy.
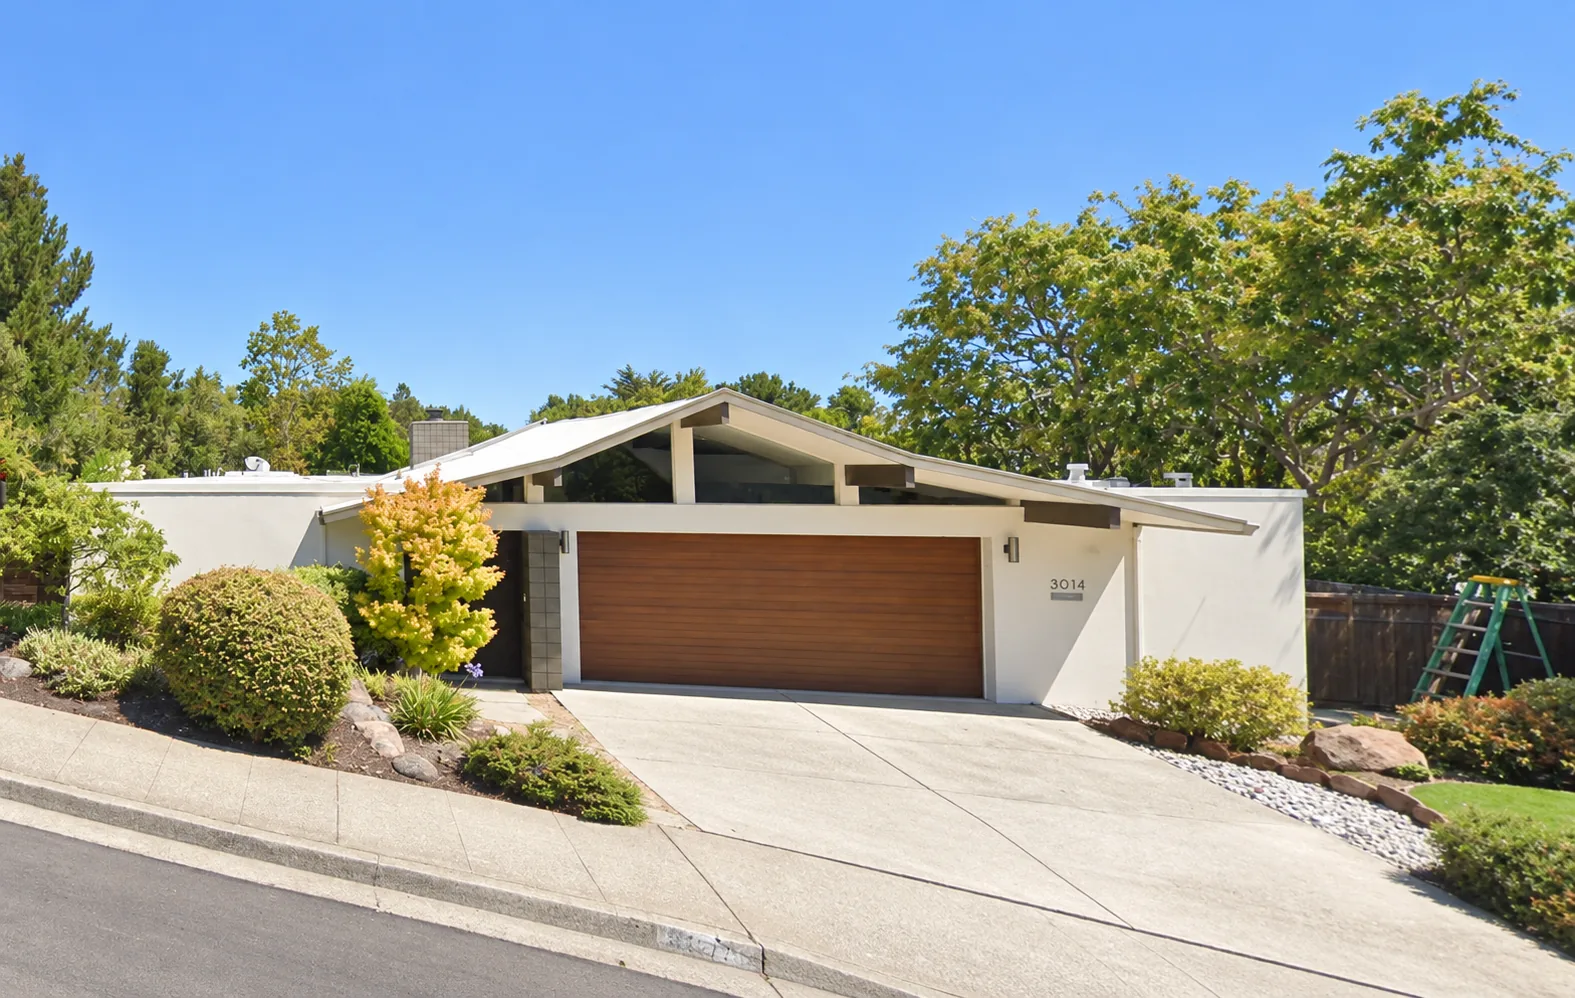
What the house is worth and what it costs to rebuild are different numbers, and insurance only cares about the second. In a 1964 post-and-beam house with a flat roof, a slab full of heating tubing and walls made of glass, the second number is higher than people expect.
Take your square footage. Multiply by $600. That is the order of magnitude Eichler Network reports as realistic for Peninsula reconstruction today, against the $300 owners have historically assumed. Now go and look at your declarations page.
Why the number moved
“Replace in kind” means rebuilding a 1964 house to 2026 code.
A rebuilt Eichler is not the house that burned down. It is that house's plan, proportions and detailing, delivered under current structural, energy, glazing, electrical and accessibility requirements — by a contractor who, as one Eichler builder puts it, has a great deal more to be responsible for than the original crew did.
The encouraging part of the same account: most Eichlers can be rebuilt. The expensive part is that the details that make it an Eichler — the beam spans, the glass walls, the flush thresholds — are the details that a code-compliant rebuild has to work hardest to reproduce.
Worked example, using the reported Peninsula figure:
| House | At $300/sq ft | At $600/sq ft |
|---|---|---|
| 2,135 sq ft | $640,500 | $1,281,000 |
| 2,230 sq ft | $669,000 | $1,338,000 |
| 2,440 sq ft | $732,000 | $1,464,000 |
Those are the three verified floor areas in this tract, multiplied out. The arithmetic is ours; the per-foot figures are Eichler Network's and are an order of magnitude, not a quote. A rebuild estimate for your specific house is a job for a contractor or a replacement-cost estimator.
The roof problem
Flat roofs are a restricted category now, and the FAIR Plan counts to 25.
Several of California's largest carriers restrict or decline flat and low-slope roofs, and the driver reported is not just storm frequency but aerial imagery — underwriters can now see the condition of a roof they have never visited. An Eichler roof that is ponding, patched or simply old is visible from above in a way it was not ten years ago.
The California FAIR Plan, the insurer of last resort, applies a 25-year threshold: it will not insure a home more than 25 years old for full replacement cost unless the roof has been replaced within that window. Past it, the offer is actual cash value — the depreciated figure, which on a roof is a fraction of what replacing it costs.
What follows from that, practically:
If you are buying
Get an insurance quote during your contingency period, not after.
On a flat-roofed, sixty-year-old house, insurability is a real contingency item and not a formality. Find out what it costs and whether the roof will be accepted while you can still act on the answer.
The four things an underwriter will ask about in this architecture: the roof — type, age and documentation; the electrical panel and whether the original service has been updated; the plumbing, including whether anything in the slab has been repaired or repiped; and the heating system.
Two of those four — the roof and the in-slab plumbing — are the same two items that drive the price negotiation. So the insurance call and the inspection are not separate exercises. Run them together and each one tells you what to ask about the other.
We are not insurance brokers and nothing here is advice on a specific policy. The figures above come from published reporting and are cited so you can check them. The buyer's page → · Roofs →
Talk to us
Want the rebuild-cost arithmetic for your house?
Send the square footage and roughly what has been done to it. We will run the numbers and tell you what the gap looks like — it costs nothing and it is the cheapest hour you will spend on the house.